Business Credit Stacking,
Explained.
Credit card stacking is a funding strategy that combines several credit cards, opened in a planned sequence across multiple issuers, into one larger pool of revolving capital, typically $20K–$150K, often with 0% intro APR (12–18 months typical). Trovo Capital plans and coordinates the sequence. Each issuer makes its own approval and credit-limit decisions.
Understand the preparation, costs, repayment and risks before deciding whether this approach fits.
Separate accounts. A coordinated plan.
- 01Review readiness
- 02Plan the sequence
- 03Track repayment
Each issuer decides its own approval, limit and terms.
What your funding strategy includes
Trovo Capital helps entrepreneurs and small-business owners plan and coordinate business credit card stacking. The service combines an authorized credit review, an issuer and application sequence, application guidance, and a repayment plan. You apply for the accounts; independent issuers decide approvals, limits, rates, and terms.
A readiness assessment
A review of the credit information you authorize, your existing accounts, business stage, and intended use of funds. If the timing is wrong, the next step is preparation rather than more applications.
An application plan
A proposed mix of cards selected for the agreed strategy, with issuer order and timing tailored to your profile. You review and submit each application yourself.
Guidance through issuer decisions
Preparation for applications, pending reviews, and reconsideration conversations. A smaller approval or decline is a reason to reassess the plan, not assume more applications will solve it.
A plan for repayment
Promotional end dates, repayment sources, and account-management priorities, with reviews for future options when the profile supports them. Approved credit is a borrowing limit, not cash income.
Trovo's fee and your card costs
The first conversation is free. Trovo Success has no upfront fees: a $795 application fee is due only on your first qualifying approval, plus 9.99% of qualifying new credit limits. Signature is $3,795, Pathway is $3,995 plus a 9% success fee, and Reserve is $8,995, each $250 less when paid in full. If Success produces no qualifying funding, you owe Trovo $0. Full plan details, payment options and worked examples are on the plans and pricing page, and Trovo puts the fee and payment terms in writing before you commit. Trovo's fee is separate from issuer interest, annual fees, transfer fees, and other account charges. A 0% introductory APR does not make the entire strategy free. Review the agreement for payment triggers, cancellation terms, and what applies if approvals are smaller than planned or applications are declined.
Compare the terms of current introductory APR offers and use the card paydown worksheet to check whether your expected cash flow supports the plan.
$20K–$150K
typical funding range
24–48hours
first decisions can begin
2–3weeks
funds typically accessible
12–18months
0% intro APR window (typical)
Trovo planning ranges, not quotes or guarantees. Issuer approval required. Trovo Capital provides independent strategy and coordination. We're not a lender and don't make credit decisions.
How does business credit stacking work?
You open several credit cards from different issuers in a planned order, use the combined limits for a defined purpose, and pay the balances down before each 0% intro period ends. Each issuer makes its own approval and limit decision.
A single business card might open with a $10,000 limit. On its own that funds very little. Five or six cards from different issuers, opened in the right order over a few weeks, can add up to a pool of revolving capital large enough to buy inventory, fund a hire, run an ad campaign, or place a deposit. Because the strongest products carry a 0% introductory rate, the capital costs nothing in interest during the window if the balances are paid down before it closes.
The word stacking describes the outcome. The work is in the sequence: which issuer sees the application first, which applications fit the issuer’s terms and your repayment capacity, which issuer will decline anyone with too many recent accounts, and which product carries the longest window for the profile. Recent applications and new accounts can affect subsequent decisions. A planned sequence does not guarantee approvals.
Trovo's current funding program is credit card stacking using credit cards selected for the agreed strategy, depending on the client's profile, funding target, and intended use. Trovo's service is not a loan. The cards are revolving credit accounts, and any balance used must be repaid under the issuer's terms. The cards are yours, in your name, approved by the issuer on the strength of your file. Trovo designs and coordinates the round.
Who qualifies, and what credit score do you need?
Trovo's own screening guideline is a personal score of about 720 or higher, with low utilization, few recent accounts, and a planned use and repayment source for the capital. It is our guideline, not a market rule: each issuer sets its own approval criteria.
The readiness review answers this in one conversation. As a rule of thumb, the strategy fits when most of the first list is true and none of the second is.
- Success and Signature start at a 720 personal credit score. Pathway starts at 650 for clients who need readiness advising before funding.
- Utilization under roughly 30% across existing cards, and no late payments in the last 24 months.
- No more than 4 new accounts opened in the last 24 months, so the strongest issuers are still available.
- An operating business, a new LLC, or a side venture with a plan. Sole proprietors can qualify with several issuers.
- A use of funds that produces a return or completes a project: inventory, equipment, ad spend, a hire, a deposit.
- A repayment source that does not depend on the funded project going perfectly.
- A profile that is not funding-ready today. Pathway starts at 650 and focuses on individual preparation; below 650, speak with an advisor before choosing a plan.
- More than 4 new cards in 24 months, which shrinks the sequence to the smaller issuers.
- A need for cash with no plan to pay it down, or an intent to take cash advances.
- Industries most issuers exclude, or an application that would require overstating revenue or misrepresenting the business.
- An existing stack of merchant cash advances or short-term loans. That is a debt-stack audit, not a new round.
Not sure which list you are on? The free funding check estimates it in a few minutes, with no inquiry.
How do we choose the right cards?
AI-assisted research and an advisor review help shape your bank list, product choices and application sequence. We consider your credit profile, business information, existing relationships and intended use of funds. Your advisor explains the proposed products and responsibilities before you decide to apply.
What are the steps, and how long does a round take?
Eight steps, from a soft-pull readiness review through issuer sequencing and your approval of each application to a written paydown plan. Strategy takes days; then initial issuer decisions can begin within 24–48 hours of your first applications, and funds are typically accessible within 2–3 weeks.
Those timings are Trovo planning ranges, not guarantees. Complex profiles take longer, and the pace always depends on the issuers.
Step 1: Soft-pull readiness review
We start with a soft inquiry you authorize. It does not touch your score and is not visible to other lenders.
The review reads your personal file, and your business file where one exists, the way an issuer's underwriter will read it: scores, utilization on every revolving account, age of accounts, recent inquiries, and any derogatory marks. If the file is not ready, you hear that first, along with what would change the answer. Nothing is applied for at this stage.
Step 2: Profile analysis and funding target
Your profile, business stage, and intended use of funds set a realistic target inside the typical range.
Two owners with the same score can have very different ceilings. Time in business, revenue, existing card limits, and whether a bank relationship already exists all move the number. The analysis produces a target inside the $20K–$150K range, and a candid note when the profile points to the low end, or to waiting.
Step 3: Issuer selection and sequence
We rank the issuers whose underwriting fits your profile and order the applications so each one sees the strongest possible file.
Every issuer has its own velocity rules, bureau preferences, and appetite for new businesses. Applying in the wrong order can lock an owner out of the strongest issuer for two years. The sequence sets which issuer goes first, which applications can go the same day, and which wait 30 days or more. The mix may be cards selected for the agreed strategy.
Step 4: You review and approve every application
Nothing is submitted without your review. You see each issuer, each product, and each requested limit before it goes out.
You are the applicant on every form, and the information on every application has to be accurate and consistent. We prepare the sequence, the timing, and the field-by-field guidance; you confirm each one. Trovo never applies on your behalf, never holds your logins, and never touches the funds.
Step 5: Initial decisions can begin within 24–48 hours
Initial issuer decisions can begin within 24–48 hours of your first applications.
Some issuers decide instantly; others place an application in review for a week or more. A pending decision is normal and often improves on a reconsideration call, which we prepare you for. A decline on one issuer is data for the next step, not the end of the round.
Step 6: Funds are typically accessible within 2–3 weeks
Funds are typically accessible within 2–3 weeks, once cards arrive and are activated.
Cards ship after approval, then activate. How you use the limit depends on the plan: paying vendors and ad platforms directly is the cheapest path; balance transfers to a checking account carry a fee of a few percent; cash advances are avoided entirely because they lose the intro rate and add fees.
Step 7: 0% intro APR, 12–18 months typical
Qualifying products carry 0% intro APR, typically 12–18 months; promotional periods range 7–24 billing cycles, depending on the issuer. The window is a benefit to plan around, not a deadline to forget.
The intro period starts at account opening, not at first use. We record each card's promotional end date at funding so nothing quietly converts to the regular rate. Later in the window, balance-transfer offers, credit-limit increases, and a second round can extend the runway when the profile supports it.
Step 8: Paydown plan and ongoing reviews
A written plan sets how the balances come down before the promotional rates end, with statement dates and utilization targets.
The plan pairs each balance with its source of repayment and its promotional end date, then sets a monthly rhythm: pay before the statement closes to keep reported utilization low, keep every account current, and review the portfolio for limit increases and next-round timing. Funding day is the start of the plan, not the finish.
What are the risks of credit card stacking?
Six to know first: personal liability under the guarantee, the regular APR after the intro period, a possible drop in your personal score, cash-advance costs, more accounts to manage, and borrowing more than the business can repay.
Revolving credit is a tool. Used with a plan it is among the cheapest capital a small business can access. Used without one it is expensive debt with your name on it.
Are you personally liable for business card balances?
Usually, yes. Nearly every small-business card requires the owner's personal guarantee. If the business cannot pay, you owe the balance personally. Treat every business card balance as your own debt, because legally it is.
What rate applies after the 0% intro period?
The regular APR applies to whatever is left, and on current business card terms that is often in the high teens to high twenties. On a large balance that is thousands of dollars a year. The paydown plan exists for this moment.
Sources: CFPB: 0% promotions vs deferred interest; Chase Ink Business Unlimited terms (16.99%–24.99% variable APR after the intro period); Capital One Spark Cash Select terms (16.99%–26.99% variable APR after the intro period)
Does stacking hurt your credit score?
It can lower your personal score. myFICO says one additional hard inquiry takes fewer than five points off most people's FICO Scores and counts toward those scores for one year, and new accounts can also affect the score. The size and duration of any change depend on the full credit file, reporting, utilization and payment history. Discuss any upcoming mortgage or auto application before opening new accounts.
Can you turn stacked cards into cash?
Not without losing the benefit. Pulling cash from a card, directly or through a workaround, is usually billed at a higher cash-advance rate from day one with an added fee. The strategy assumes purchases and, where the terms allow, balance transfers, never cash advances.
Source: CFPB: credit card cash advances
More accounts, more to manage
Six or eight cards mean six or eight statement dates, due dates, and promotional end dates. A missed payment can end an intro rate early and mark the file. A tracking system is part of the plan, not an afterthought.
Over-leverage
A large approved limit is not income. If the funded project does not earn more than the eventual interest cost, the guarantee turns into personal financial stress. We will tell you when the sensible answer is a smaller round or no round.
try the numbers
Plan the paydown before the spending.
Use your actual promotional end date and a budget the business can support. This illustration targets repayment one month early when time allows.
Monthly principal target
$1,818.19
Over 11 months, leaving a one-month buffer.
Your entered budget meets this target.
- Balance at promotional expiry
- $0.00
- Months at your budget, at 0%
- 10
Any balance after expiry can accrue interest. The months-at-budget figure assumes 0% throughout and is not a forecast after that date.
Assumptions: 0% purchase APR for the full period entered, equal monthly payments, no fees and no new spending. This divides principal across the chosen months; it does not calculate an issuer’s minimum payment, approval odds or affordability. Actual statement dates, fees and account terms control. No information entered here is submitted to Trovo.
Track each account in the paydown worksheetShould you use a stacking company or do it yourself?
You can run a round yourself if you know each issuer's rules, have the weeks to run the sequence, and can handle pending decisions. A coordinator mainly adds a set issuer order, scheduled timing and prepared reconsideration calls.
Nothing in this strategy is secret. Every issuer's application is public, and a patient owner with a strong file can open several cards alone. The difference is what a coordinator knows going in, and what a mistake costs when you learn it on your own file.
| Decision | On your own | With a coordinator |
|---|---|---|
| Issuer order | You learn each issuer's velocity rules and bureau preferences as you go. The first decline is usually how you find out. | The sequence is set before the first application, so the strictest issuer sees the cleanest file. |
| Timing | Applications go out when you have a free evening. Same-day windows and waiting periods are easy to miss. | Same-day batches and waiting periods are scheduled around statement dates and bureau updates. |
| Pending decisions | A pending or declined application is a dead end unless you know reconsideration exists and what to say on the call. | Every pending decision gets a prepared reconsideration call. A decline becomes data for the next step. |
| The paydown plan | Often written after the cards arrive, if it is written at all. | Written before funding, with every promotional end date recorded on day one. |
| What it costs you | Your time, plus whatever a wrong order costs the round. A wrong order can close the strongest issuer to you for a long stretch. | A fee for the strategy, discussed in the first conversation and put in writing before you commit to anything. |
The plain test: if you already know your issuers' rules, have the weeks to run the sequence, and would not lose sleep over a pending decision, do it yourself. If the round is worth more to you than the time it takes to learn, that is the case for a coordinator. Either way, the free funding check tells you whether the profile is ready at all.
How do you check if a credit stacking company is legitimate?
Run six checks: confirm the legal entity and address, make sure you are the applicant, get pricing in writing, walk away from guarantees, start with a soft pull, and read the cancellation terms. Run every one on Trovo too.
Funding coordination attracts good operators and bad ones, and the pitch sounds the same from both. Six checks separate them. Run every one on Trovo Capital: our registration, identity and licensing details are on the verification page, and the rest we answer in the first conversation, in writing.
Check 1: Confirm the legal entity and the address
Ask for the registered legal name and entity number, then look them up in the state business registry yourself. A real office address and a phone number someone answers are the baseline. A company that will not name its entity has a reason.
Check 2: Ask who submits the applications
You should be the applicant on every form, with the right to review each one before it goes out. A company that applies for you, holds your logins, or asks for account access is taking a risk with your name on it.
Check 3: Get the pricing in writing before you sign
The fee, when it is due, and what happens if the round comes in smaller than planned belong in the agreement, not in a phone call. Anyone who will not put pricing in writing has told you what you need to know.
Check 4: Listen for guarantees
No one outside the issuer decides an approval. A promised amount, a promised approval, or a promised timeline is a sales tactic, not a plan. Expect a range and a candid read on your profile instead.
Check 5: Check how your credit is reviewed
The first look at your file should be a soft inquiry you authorize, with no hard pull until you choose to apply for a specific card. Ask exactly what you are authorizing and how to revoke it.
Check 6: Read the cancellation terms
You can cancel in writing before your program starts with no Trovo fee, and any payment is refunded. Pathway and Reserve also include a no-charge cancellation period through the fifth business day after signing. Your signed agreement spells out the terms. Wherever you are, know how you exit before you enter.
Entity number, insurance, office, and phone, on one page.
Strategy and coordination. Not a lender, not a broker.
- Reads your authorized credit data and tells you candidly whether the timing is right.
- Designs the issuer sequence, timing windows, and card mix for your profile and use of funds.
- Prepares you for each application, pending review, and reconsideration call.
- Records every promotional end date and builds the paydown plan with you.
- Reviews the portfolio after funding for limit increases, balance-transfer windows, and next-round timing.
- Lend money, broker loans, or make credit decisions. Banks and card issuers decide every approval, limit, rate, and term.
- Submit applications for you, hold your logins, or take possession of your funds.
- Guarantee any funding amount, approval, or timeline.
- Do credit repair. If the file needs work, we say so and point you to a specialist.
- Advise you to misstate revenue, ownership, or the purpose of a card. Accurate applications are the whole strategy.
See an illustrative $30K strategy map
Example only. A new business plans $22,000 of inventory purchases and an $8,000 marketing test. The owner has a strong stated personal credit range. No approval, issuer, limit or offer is assumed.
- Preparation
- Confirm the owner’s full credit file with authorization, current balances, reporting dates and the business details each proposed issuer requires. New-business status becomes part of the strategy.
- Product and sequence
- The map identifies each proposed account, verified offer terms, eligible uses, application order and the reason for that choice. You review each step before an application. A decline or changed term triggers a reassessment.
- Repayment
- $30,000 divided by a $3,000 monthly principal budget is 10 months. That is arithmetic, not an affordability assessment. Test the budget against actual cash flow and the verified promotional end date. Allow separately for fees and other charges.
- Decision points
- If the purchase is ineligible, the repayment budget does not hold, or approved capacity falls short, reduce or phase the project and reassess the funding path. Card capacity is not automatically cash deposited into a bank account.
- Your handoff
- A proposed account sequence, use-of-funds plan, payment calendar and questions to resolve with your Trovo specialist. Trovo’s service scope and fee are put in writing before you commit.
Illustrative planning example, not an offer, customer outcome or recommendation to apply. Issuers determine approvals, limits, pricing and eligible transactions.
Business credit stacking FAQ
How much does Trovo's credit stacking service cost?
The first conversation is free. Trovo Success has no upfront fees: a $795 application fee is due only on your first qualifying approval, plus 9.99% of qualifying new credit limits. Signature is $3,795, Pathway is $3,995 plus a 9% success fee, and Reserve is $8,995, each $250 less when paid in full. If Success produces no qualifying funding, you owe Trovo $0. Full plan details, payment options and worked examples are on the plans and pricing page, and Trovo puts the fee and payment terms in writing before you commit. Trovo's fee is separate from issuer interest, annual fees, transfer fees, and other account charges. A 0% introductory APR does not make the entire strategy free. Review the agreement for payment triggers, cancellation terms, and what applies if approvals are smaller than planned or applications are declined.
What if I'm denied or my approvals are smaller than planned?
An issuer may approve less than requested, decline an application, or ask for more information. Trovo reviews the result and the next step with you; neither the target range nor an initial approval guarantees the rest of a round. Your written agreement controls Trovo's fees and payment obligations. Ask how partial approvals, declined applications, and stopping a round affect those obligations before signing.
What rules apply to credit card stacking?
Every application must be accurate and comply with the issuer's eligibility and account terms. Never misrepresent revenue, ownership, identity or intended use. Credit card stacking does not bypass underwriting or remove repayment obligations. Approvals are never guaranteed. Trovo coordinates the strategy; issuers decide each application.
How will the cards affect my personal credit?
Applications can lower your personal score slightly: myFICO says one additional hard inquiry takes fewer than five points off most people's FICO Scores and counts toward those scores for one year. Personal credit cards generally report the account, balance, and utilization to consumer credit bureaus. Many business cards do not routinely report ongoing activity to consumer bureaus while the account remains in good standing, but issuer policies vary and can change. Applications may involve hard inquiries, and many small-business cards require a personal guarantee. Late payments, defaults, or other negative activity can affect your personal credit and may create personal liability.
Do I need an established business to qualify?
An established business is not required for every card product. The appropriate strategy depends on the issuer's requirements, business stage and your profile. We review your business stage, records, intended use and repayment plan before recommending next steps. No business age or credit score guarantees an approval.
What happens when the 0% intro period ends?
The regular purchase APR applies to any remaining balance under the issuer's terms. Promotional windows range 7–24 billing cycles, depending on the issuer; 12–18 months typical is a planning reference, not a guaranteed offer. Set a repayment plan using the actual end date and fees for each account. Do not assume another promotional offer or funding round will be available to repay the balance.
Sources: CFPB: how long an introductory rate lasts; CFPB: 0% promotions vs deferred interest
How is this different from a business loan or a merchant cash advance?
Credit cards provide revolving limits, with any introductory rate limited to the qualifying transactions and period in the offer. A term loan has an agreed repayment schedule. Merchant cash advances use a different repayment and pricing structure, often tied to business receipts. Compare the actual cost, payment frequency, guarantees and repayment capacity. Trovo's current funding service coordinates card strategies; the other paths on our comparison page are educational, not products Trovo offers or arranges.
Does Trovo apply for the cards on my behalf?
You are the applicant and review and approve every application. Trovo plans the sequence and timing, helps you prepare accurate information, and coordinates the next steps. We do not apply without your authorization. Each issuer makes its own approval and credit-limit decisions; Trovo is not a lender.
More answers in the full FAQ, and every term on this page is defined in the funding glossary.
Two guides. No email gate.
The playbook walks the whole round: readiness factors, the 60-second rubric, how 0% intro APR funding works, sequencing, and a 30-day roadmap. The checklist is the printable version of the readiness rows.
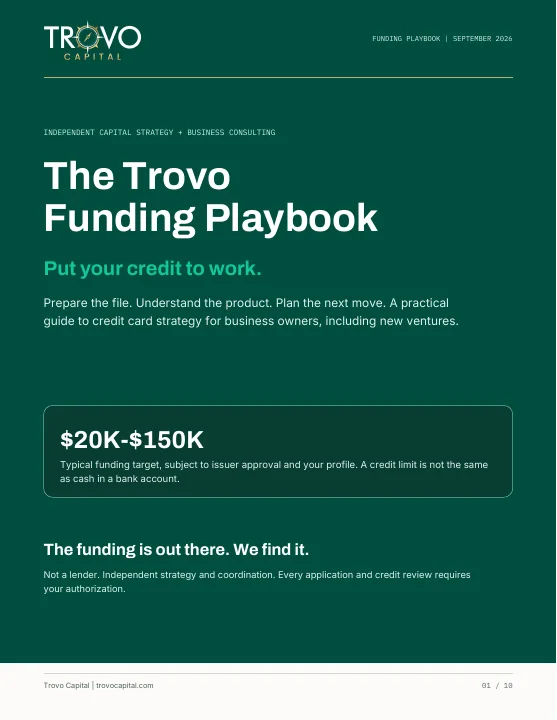
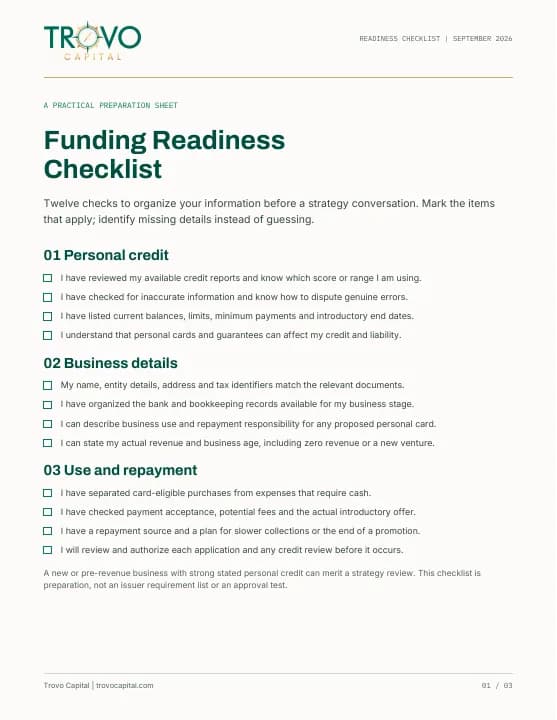
The 0% intro APR library
The guides behind each step of the round, published in full.
One Trovo team.
A plan that fits your starting point.
Compare preparation, capital strategy and ongoing advisory support. Choose by readiness, payment preference and how much ongoing support you want. Website, CRM and growth delivery are scoped with you separately.
Not sure? Get help choosing a plan.
Compare qualifications, included support and total costs before choosing.
Trovo Success
Ready for funding. No upfront fees.
02 / Ready for fundingTrovo Signature
Ready for funding. A fixed fee, no percentage.
03 / Get funding-readyTrovo Pathway
Not qualifying for funding today? Start with preparation.
04 / VIP advisoryTrovo Reserve
Extended guidance. VIP support. A partner included.
Ready to see your
funding map?
Tell us where you are. We will map a realistic path to $20K–$150K in funding and tell you candidly if the timing is not right.